If you have ten minutes a week to manage money, a budget that requires you to log every purchase probably will not last. Start with what you can reliably keep up. For some households, that is a weekly check of account balances and upcoming bills. Others need limits on everyday spending because small purchases keep crowding out bigger plans.
A budget does not need to account perfectly for every purchase you made last month. It needs to show what you can spend now and flag trouble while there is still time to respond. The best method is the one that gives you that information without demanding more attention than you can spare.
Start with the decisions the budget must support
Before choosing an app, spreadsheet, or notebook, work out what you need help deciding. Do bills come due before income arrives? Is grocery spending hard to predict? Do annual costs keep catching you off guard? Do two people need to see how much shared money is available? Those problems call for different levels of detail.
Look at one or two months of account and card activity, along with bills that come less often. Group costs into recurring essentials, day-to-day spending, and irregular expenses such as repairs, travel, or insurance renewals. Put minimum debt payments with recurring bills, but show extra payments separately: one is required, the other is a choice. If your income varies, plan around the lowest month you can reasonably expect rather than your best one.
A short budget is not necessarily an incomplete budget. If you can see rent, utilities, groceries, transport, minimum debt payments, and money set aside for irregular costs, you may already have enough to make better decisions. Add categories when they change what you do, not just to make the record look thorough.
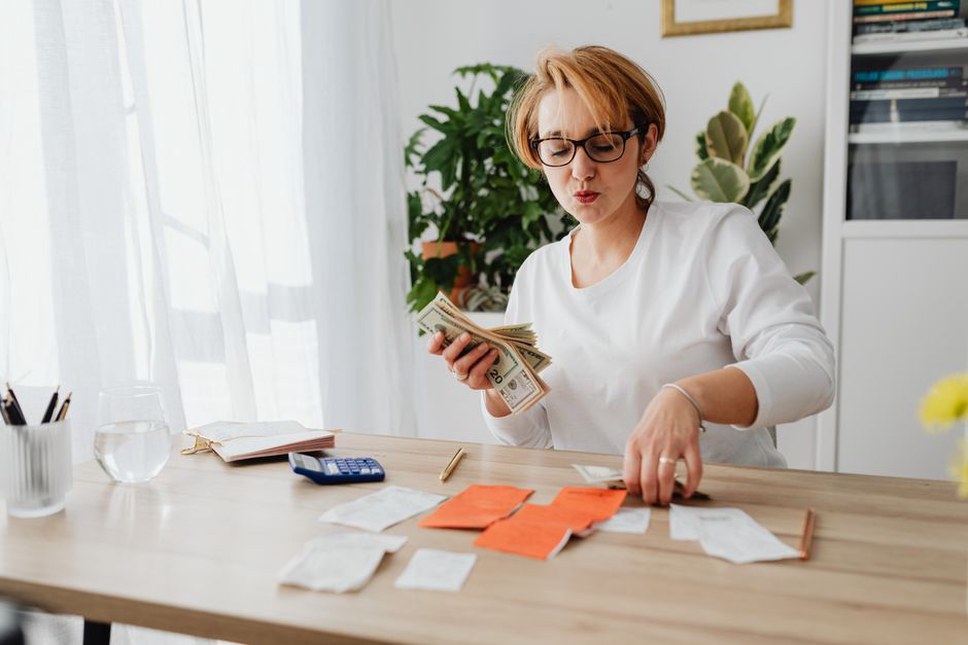
Match the method to your main constraint
Use a simple category plan when you need broad limits
A category plan gives monthly limits to groups such as food, transport, household needs, and leisure. It suits fairly predictable income and people who want boundaries without logging every transaction. Check the categories once a week in a spreadsheet, notes app, or paper ledger. A percentage-based plan is another option, dividing income among essentials, discretionary spending, and savings. Use the percentages as a starting point, though: housing costs, income, and existing obligations may make a standard split unworkable.
Too many categories make the plan harder to use. Separate takeaway meals from groceries if they call for different decisions. If shampoo and cleaning supplies rarely cause a problem, one household category will do. A category that never changes a spending choice probably does not need its own line.
Use zero-based planning when every dollar needs a job
In a zero-based budget, you assign all available money to spending, saving, or debt payments until nothing is left unassigned. That does not mean spending it all. Money held for next month’s rent or a future repair has a job. This method helps when money is tight, goals compete, or an unexpected cost means choosing which category to draw from.
You do need to update it regularly. If transport costs more than planned, move money from another category instead of leaving a plan you know is wrong. Assign money you have received, especially when pay dates or amounts are uncertain. A projected paycheck can help you prepare for bills; it cannot pay for today’s purchase.
Use envelopes for spending that needs a firm stop
Cash envelopes make a limit hard to miss. When the grocery envelope is empty, you stop spending, change the plan, or consciously move money from another envelope. Digital envelopes use separate accounts or tracked balances to do much the same thing. They can help contain categories that tend to grow, though they are less convenient for online purchases and automatic bills.
There is no need to put the whole household budget into envelopes. Start with a few troublesome categories, and allow a small buffer for necessary variation. A grocery limit that cannot absorb a week of higher food prices will lead to constant exceptions.
Use a bills-first or pay-period plan when timing is the problem
An account balance can look healthy just before several bills are paid. If timing keeps causing trouble, list each payday and due date, set aside required payments, and work out what remains until the next payday. This is useful when pay comes weekly or fortnightly, income is uneven, or a large bill falls early in the month.
A calendar or basic account forecast may tell you more than detailed spending categories. Estimate deposits conservatively, mark automatic payments, and allow for transactions that take time to clear. Money in the account is not necessarily safe to spend if rent has yet to come out.
Choose a tracking level you can maintain
Budget methods differ in upkeep as much as in arithmetic. One person is happy to enter transactions each evening; another can reliably manage a fifteen-minute weekly review. If the weekly review is what you will actually do, choose it. Approximate categories checked regularly beat a detailed system abandoned after two weeks.
- Low-touch: Automate bills and savings where feasible, check upcoming payments, and review broad spending totals weekly or monthly. This suits stable finances, but you may spot overspending late in the cycle.
- Weekly category check: Compare spending with a few limits and adjust your plans for the rest of the month. You get feedback without entering every purchase by hand.
- Transaction-level tracking: Log or import each expense and assign it to a category. The detail can help when margins are narrow or several people share spending decisions, but it takes more upkeep.
Automation saves typing, not judgment. Imported transactions may arrive late or be mislabeled, and moving money between your own accounts is not a new expense. If you use an app, check its shared-access options, exports, and account permissions. A notebook or offline spreadsheet may suit you better if you do not want to connect financial accounts. In either case, protect access to sensitive financial information.
Account for the costs that do not fit neatly into a month
A budget can seem fine until a car service, annual membership, medical bill, or equipment replacement comes along. Set aside money each pay period for irregular costs you can foresee. If an annual expense is $600, saving $50 a month makes the bill easier to handle. For less predictable costs, begin with a modest amount and adjust it as you learn what a typical year costs.
Keep that money separate from an emergency fund if you can. An insurance renewal is not an emergency just because it comes once a year. If you cannot save for every irregular expense straight away, list what is due soonest and which missed payments would have the greatest consequences. Funding everything equally may leave the most pressing bill short.
The same distinction matters for a volunteer project or small music archive. Routine hosting fees, occasional storage supplies, and a possible equipment failure each need different treatment. If you keep a separate archive account, choosing a bank account for a small music archive deals with where the money sits; the budget shows how much the account needs for its obligations.
Test the method against a real month
Try one approach for four to six weeks before switching systems. Write down expected income, required bills, a few spending limits, and money reserved for later costs. Pick a review time you can repeat, perhaps Sunday evening or the day after payday. As you go, notice where the method falls short rather than treating every difficulty as a personal failure.
At the review, ask:
- Could you tell what was safe to spend before making a nonessential purchase?
- Did you catch a bill or spending problem early enough to respond?
- How long did updates take, and did you actually do them?
- Which categories changed a decision, and which only added paperwork?
- Could the plan handle an ordinary surprise without hiding the trade-off?
If updating takes too long, combine categories or replace daily logging with weekly checks. If you run short before payday while staying within monthly limits, add a pay-period calendar. If discretionary spending is hard to account for, track transactions in that area alone for a while. Make one change at a time so you can tell whether it helped.
Make room for other people and changing circumstances
With shared finances, agree on which costs are shared, who records them, and when you will review the plan together. Relying on one person to interpret every purchase can create confusion. Decide when an unplanned shared expense needs discussion, and leave each person some money they need not explain line by line. That agreement matters more than the app you use.
A change in income, moving costs, or debt payments can make last month’s limits obsolete. Rework the baseline after a major change instead of squeezing new circumstances into old categories. If essential costs exceed reliable income, a different budget format will not close the gap. The plan should make the shortfall visible so you can prioritize obligations and consider available support or changes.
At your next review, correct one number and name where the money will come from. If groceries need another $25, move $25 from an unspent category and record the transfer. The plan stays honest, and you do not have to start the month over.